
Business & asset finance
Equipment finance
Get the machinery, tools and technology your business needs without tying up your cash flow.
What we can finance
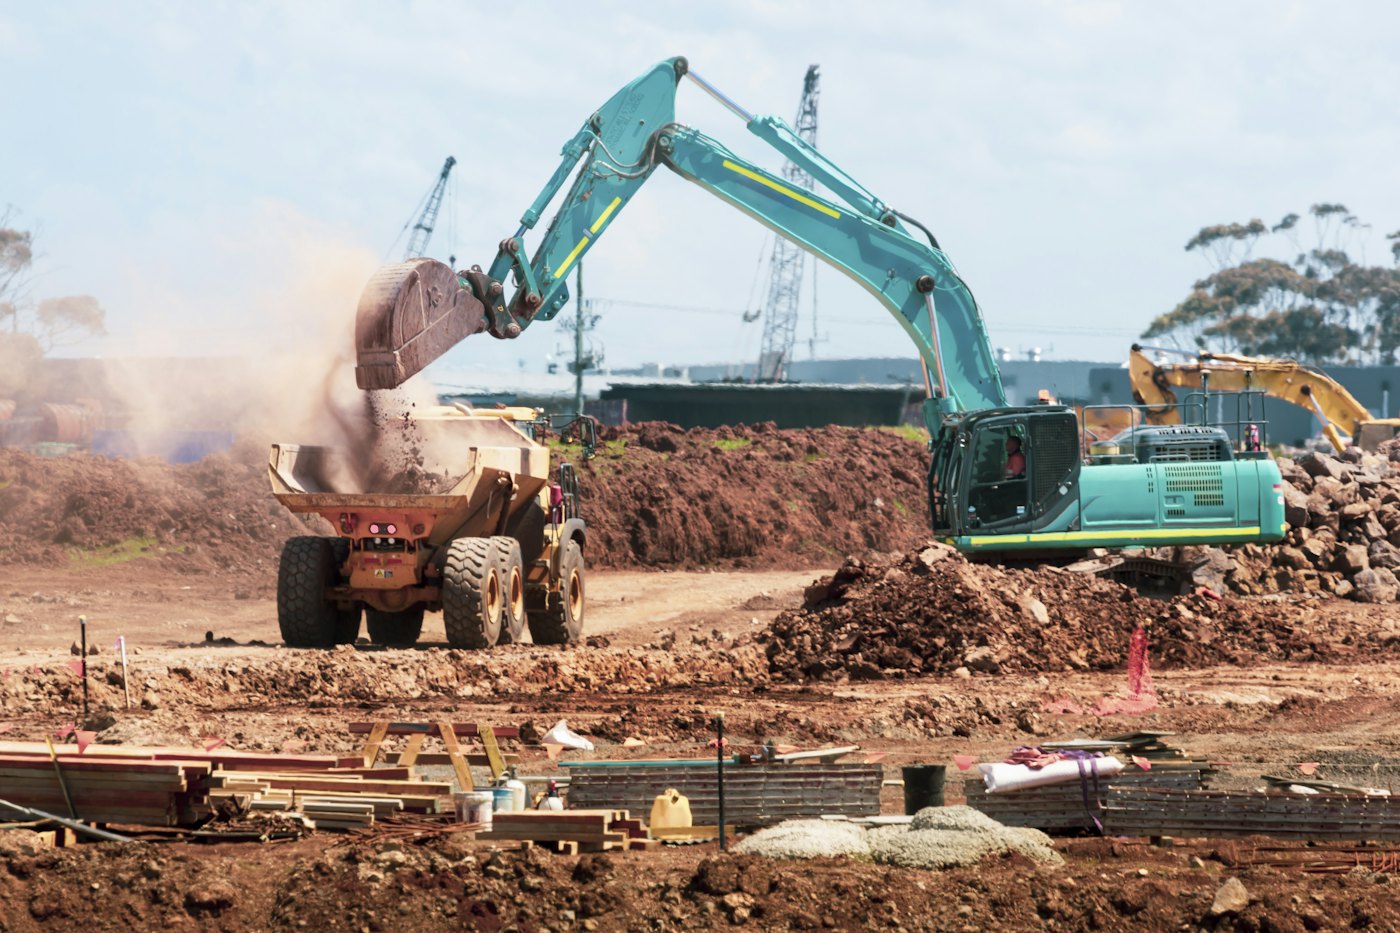
Construction and earthmoving machinery, trade tools, hospitality and commercial kitchen equipment, medical and dental equipment, IT and office fit-outs, and manufacturing plant. New or used, from dealers or private sellers.
Finance options
- Chattel mortgage: you own the equipment from day one and the lender takes security over it.
- Finance lease: the lender owns the equipment and you lease it, with an option to buy at the end.
- Hire purchase: ownership passes to you once the final payment is made.
- Balloon or residual payments: to lower regular repayments.
The right structure depends on your business and tax position, so we recommend confirming it with your accountant.
Why finance equipment instead of paying cash?
Financing spreads the cost over the working life of the equipment, so your cash stays available for wages, stock and growth. Repayments are fixed, which makes budgeting easier, and the equipment itself is usually the security, so you often don’t need to put your home on the line.
What lenders usually need
Your ABN, time in business, recent BAS or financials for larger amounts, and the quote or invoice for the equipment. Many lenders offer streamlined, low-doc approvals for established businesses. Answer a few quick questions to get started, or see vehicle finance for cars, utes and trucks.
Ready to talk?
Answer a few quick questions and a broker will come back to you within one business day.
Related services
FAQ
Common questions
What is a chattel mortgage?
A chattel mortgage is a business loan where you own the equipment from the start and the lender holds security over it until the loan is repaid. It’s one of the most common ways Australian businesses finance equipment and vehicles.
Can I finance used equipment or buy from a private seller?
Yes, many lenders finance used equipment and private sales, although the age of the equipment and the seller type can affect the options and pricing available.
Can I get equipment finance with a new ABN?
Some lenders will consider businesses that have been trading for less than two years, particularly if you have industry experience, a deposit or property as extra security.
What is a balloon payment?
A balloon is a lump sum due at the end of the term. It lowers your regular repayments but means you’ll need to pay, refinance or trade in at the end, so it should match your plans for the equipment.
Can I claim GST on equipment finance?
If your business is registered for GST, you may be able to claim GST credits depending on the finance structure. Your accountant can confirm how it applies to you.
Found the equipment you need?
Send us the invoice or quote details and we’ll come back to you within one business day.

